Education & Family Benefits
Your service earned more than a discharge paper. It earned a college degree, a trade certification, a monthly housing allowance while you study, and, if you are rated 100% or gave everything, education and healthcare for your children, too. These are not loans, not scholarships, and not charity. They are earned benefits, every one of them, and I wrote this page to walk you through all of them in plain English so you know exactly what you have, what your family has, and how to use it. But the VA does not add dependents automatically. You have to file the forms, and that part is on you.
30-Second Family Benefits Check
Answer yes or no to each question. Every “yes” means money, healthcare, or education your family may be leaving on the table right now. You do not need to know the details yet — that is what the rest of this page is for.
Is your combined VA rating 30% or higher?
If yes → You qualify for additional monthly compensation for a spouse, children, and dependent parents. File VA Form 21-686c if you have not already.
Are you rated 100% permanent and total (P&T)?
If yes → Your spouse and children likely qualify for CHAMPVA healthcare AND DEA Chapter 35 education benefits — both are frequently missed.
Did you serve on active duty after September 10, 2001?
If yes → You almost certainly earned the Post-9/11 GI Bill. If you are still serving, you may be able to transfer unused months to your spouse or children.
Do you have dependents not yet on your VA award?
If yes → Every month a qualifying dependent is missing from your award is money the VA is not paying you. Back pay runs from the date you file the 21-686c.
Has a service member in your family died in the line of duty or from a service-connected condition?
If yes → The surviving spouse and children may qualify for DIC ($1,612.74/month, tax-free), the Fry Scholarship, DEA Chapter 35, and CHAMPVA.
Do you have a service-connected disability and want to change careers or finish a degree?
If yes → VR&E Chapter 31 is a separate entitlement from the GI Bill — it does not consume your GI Bill months — and covers tuition, books, supplies, and a monthly subsistence allowance.
What These Benefits Are Worth
These are the real dollar values behind the programs on this page — not projections, not averages, but the published rates. Every cent is earned, tax-free at both the federal and state level, and never repaid: VA compensation and dependency benefits are not loans, not need-based welfare, and not subject to income tax reporting. Dependents matter more than most veterans realize. Once your combined rating hits 30%, adding a spouse, a child, or a dependent parent to your award increases your monthly check for as long as they qualify — and the VA does not add them automatically. You have to file the 21-686c. Children stay on the award to age 18, or to 23 if they remain in school full time, and a child who became permanently disabled before turning 18 can stay on it for life. Read the numbers below with that in mind: the difference between filing and not filing is frequently thousands of dollars a year that nobody will ever call to tell you about.
Per year at private or foreign schools under the Post-9/11 GI Bill and Fry Scholarship (2025–2026 academic year).
Monthly payment for a full-time student under DEA Chapter 35 (rate effective October 1, 2025).
The GI Bill provides up to 36 months; VR&E (Chapter 31) provides up to 48 months — and they are separate entitlements.
Every benefit on this page is earned, not borrowed. None of it is a loan, and nothing is ever repaid.
Five Ways the VA Pays for Education
Two programs for you. Three programs for your family. Each one below has its own full guide — who qualifies, what it covers, how to apply, and the mistakes that cost families the most. Tap any card to open its complete walkthrough.
For the veteran
For your family
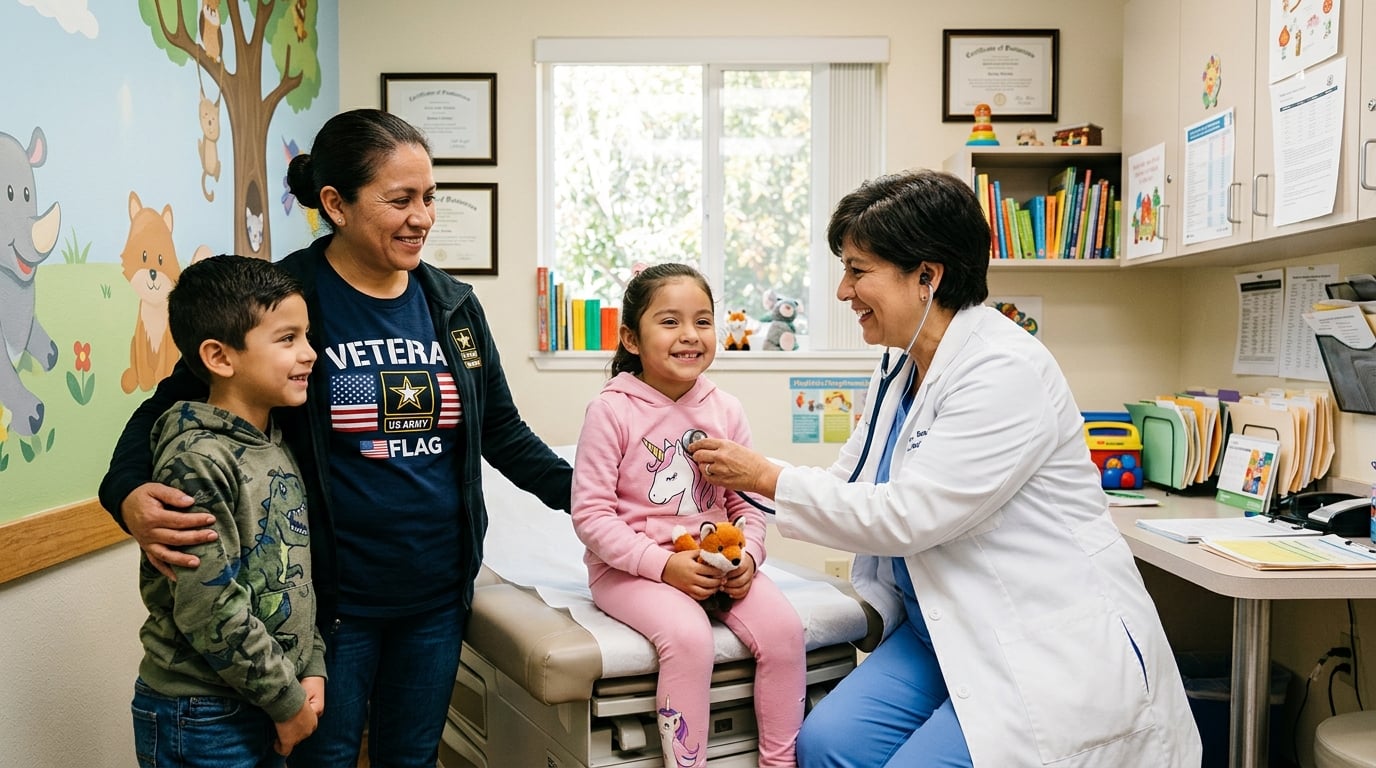
CHAMPVA: Health Coverage for Your Family
If you are rated permanently and totally (100%) disabled from a service-connected condition, your spouse and children may qualify for CHAMPVA — a VA health program that shares the cost of their medical care, much like insurance. The same rating that unlocks DEA education benefits for your children can also cover their doctor visits, prescriptions, mental health care, and hospital stays.
- Covers doctor visits, prescriptions, mental health, hospital stays, and preventive care for your spouse and children.
- No enrollment fee. Minimal copays. The VA shares the cost the way an insurance plan would.
- Your family can see most civilian providers who accept CHAMPVA — you are not limited to VA facilities.
- Many families qualify for both DEA and CHAMPVA at the same time and never realize it. If your rating is P&T, check both.
Survivor Benefits — DIC, Survivors Pension & Aid & Attendance
When a veteran dies from a service-connected condition — or within 10 years of leaving the military with a continuously-rated service-connected disability — the surviving spouse and dependent children may be entitled to Dependency and Indemnity Compensation (DIC). DIC is a tax-free monthly payment that recognizes the sacrifice the whole family made. It is separate from the veteran’s disability compensation, separate from SGLI/VGLI life insurance, and it does not reduce any other benefit the family is already receiving.
If the veteran’s death was not service-connected but the veteran had wartime service and the family’s income falls below VA thresholds, the Survivors Pension (VA Form 21P-534EZ) may still apply. And for surviving spouses who need help with daily activities or are housebound, Aid and Attendance adds a monthly amount on top of DIC or the Survivors Pension.
DIC — Dependency & Indemnity Compensation
The base DIC rate for a surviving spouse is $1,612.74 per month (2025), tax-free. Additional amounts are paid for each dependent child, for a spouse who is housebound or needs aid and attendance, and for a surviving spouse who was married to the veteran for 8+ years. File with VA Form 21P-534EZ.
VA Benefits: 800-827-1000
Survivors Pension (Non-Service-Connected)
If the veteran’s death was not caused by service but the veteran had qualifying wartime service, the surviving spouse and children may be eligible for the Survivors Pension, an income-based monthly payment. The maximum annual rate (MAPR) for a surviving spouse alone is $10,805 (2025). File with VA Form 21P-534EZ.
Aid & Attendance / Housebound
A surviving spouse who needs help with daily activities (bathing, eating, dressing) or is substantially housebound may qualify for an additional monthly allowance on top of DIC or the Survivors Pension. This can raise the effective payment by several hundred dollars a month. Evidence from a treating physician is required.
Important: DIC eligibility also extends to children under 18, children 18–23 who are in school full time, and children who became permanently disabled before age 18. The surviving spouse does not lose DIC by remarrying after age 57. These rules change periodically — confirm current eligibility with an accredited representative or the VA benefits hotline (800-827-1000).
Financial Support for You and Your Family
Once you have a service-connected rating, your monthly check is not the end of it. Adding dependents raises your payment, life insurance becomes available with no medical exam, and any back pay owed for the gap between your effective date and your claim date is money the VA is holding, not money you have to fight for. Here is what to claim and the exact forms and phone numbers to do it.
Extra Pay for Dependents (30% or Higher)
If your combined rating is 30% or higher, the VA pays you more each month for a spouse, children, and even dependent parents. You add them with VA Form 21-686c (Declaration of Status of Dependents), backed by marriage and birth certificates. Many veterans never file it and quietly lose that money every single month.
VA Benefits Hotline: 800-827-1000
Back Pay for Dependents
Dependent back pay runs from the effective date of your rating increase or the date you filed to add the dependent, whichever is later. Example: your 30% rating is effective January 1, 2022, but you did not add your spouse and child until July 1, 2022. The VA may owe you the difference for that gap as a lump sum. File the 21-686c as early as you can so this window stays small.
VALife Insurance (Up to $40,000)
Veterans with a service-connected disability can buy VALife, a guaranteed-acceptance whole life policy of up to $40,000 in $10,000 increments, with no medical exam and no health questions. Full coverage takes effect two years after enrollment as long as premiums are paid. It is one of the few life insurance options that cannot turn a disabled veteran down.
VALife Support: 800-669-8477
Direct Deposit and VA Debt
Set up or change direct deposit through your VA.gov account or the benefits hotline so payments land on time. If you ever get an overpayment notice, that is the VA Debt Management Center: you can set up a repayment plan, request a waiver, or appeal the debt. Respond promptly, because ignoring a notice is what turns a fixable error into a withheld check.
VA Debt Management Center: 800-827-0648
How to Claim These Benefits for You and Your Family
Each program has its own detailed guide (tap any card above), but here is the overview so you know where to start and in what order. The sequence that costs people the most money is getting this backwards. Add your dependents first with the 21-686c — it is the fastest change to your monthly check and it takes effect from the date you file, not the date the VA gets around to processing it. Then look at education: Chapter 35 DEA and transferred Post-9/11 GI Bill benefits are entirely separate programs with different eligibility, different payment structures, and different deadlines, and choosing the wrong one can forfeit tens of thousands of dollars of the other. Survivor benefits — DIC, and the Survivors Pension — run on their own tracks and are frequently paid at the wrong rate or missed entirely because nobody in the family knew to claim them. Start with the program that matches where you are right now, not the one with the biggest number attached to it.
Know which benefit fits your situation
If you are the veteran using the benefit yourself: Post-9/11 GI Bill (school) or VR&E Chapter 31 (career rebuilding with a disability). If your family is using it: DEA Chapter 35 (you are 100% P&T), the Fry Scholarship (service member died in the line of duty), or Transfer GI Bill (you pass your months while still serving).
Confirm your qualifying status
For the GI Bill: your DD-214 shows qualifying post-9/11 service. For DEA and CHAMPVA: your VA rating letter says "permanent and total." For VR&E: you need at least a 10% service-connected disability rating. If you are not sure, a free representative can check in minutes.
Apply with the right form
Post-9/11 GI Bill: VA Form 22-1990. DEA or Fry: VA Form 22-5490 (the dependent applies). Transfer GI Bill: milConnect (DoD, not VA). VR&E: VA Form 28-1900. All are available online at VA.gov.
Give your Certificate of Eligibility to the school
After the VA approves your application, they send a Certificate of Eligibility (COE). You hand it to your school's veterans certifying official, who verifies enrollment and starts the payments.
Get your rating right first
Your disability rating connects to everything. A higher, more accurate rating can unlock DEA for your children, CHAMPVA for your family, VR&E for your career, and tax-free income for life. Scroll down for a free, no-obligation review.
Re-check eligibility every time something changes
These programs are not decided once. A rating increase to 100% permanent and total opens DEA and CHAMPVA for your family. A new marriage, a new child, or a child turning eighteen changes who can use what and for how long. Add or update dependents with VA Form 21-686c so your record and your payments match your actual family, and re-read your eligibility any time your rating or your household changes.
Things No One Told You — But Should Have
Your GI Bill benefits never expire if you separated on or after January 1, 2013 — there is no 15-year deadline.
Using VR&E (Chapter 31) does not consume your GI Bill months — they are separate entitlements. You can use both, sequentially.
A surviving spouse does not lose Fry Scholarship eligibility upon remarriage (effective January 2, 2025).
VA disability compensation is not income — it does not count against need-based financial aid, and it does not reduce your education benefits.
You have the right to request a female advisor or counselor in any VA education program.
Official VA Links & Numbers
Everything you need to understand these programs is on this page and in each program’s full guide — you should not have to go hunting on VA.gov to learn what your family qualifies for. The links below are here in addition, for the moment you are ready to file and want the official form or the current published rate table straight from the source. When you call, have your VA file number (or Social Security number), your dependents’ full names, dates of birth, and Social Security numbers, and any marriage or divorce certificates ready — the single most common cause of a delayed dependency claim is a missing date, not a missing document. The general benefits line is 800-827-1000, weekdays, and it can confirm exactly who is currently on your award.
Education & Family Benefits — Official VA Links
All program details are on this page and in each program's full guide. These official links take you straight to the VA pages and forms.
Post-9/11 GI Bill (Chapter 33)
va.gov — your education benefit
Transfer Post-9/11 GI Bill to family
Must be done while still serving
DEA (Chapter 35)
Dependents' education for P&T families
Fry Scholarship
Post-9/11 survivor education
VR&E (Chapter 31)
Vocational rehabilitation for disabled vets
CHAMPVA
Health coverage for dependents of P&T veterans
VA Form 22-5490
Application for survivors' & dependents' education
GI Bill Comparison Tool
Compare schools, costs, and outcomes
DIC for Surviving Spouse & Dependents
va.gov — dependency & indemnity compensation
VA Form 21P-534EZ
Application for DIC, Survivors Pension, accrued
Questions? Women Veterans Call Center
1-855-829-6636Free, confidential — they can help you and your family find the right education benefit.
GI Bill Hotline: 1-888-442-4551 (Mon–Fri 8am–7pm ET)
Questions Families Ask About These Benefits
Clear answers about the GI Bill, DEA, dependent pay, and family health care — and how to tell which is worth the most for you. A free review can help you compare them honestly.
Can I transfer my GI Bill to my spouse or children?
Often, yes. If you qualify under the Post-9/11 GI Bill and meet the service commitment, you can transfer unused education benefits to your spouse or children through the Transfer of Entitlement program. The transfer must generally be requested while you are still serving, so it is worth checking the rules early.
What is DEA / Chapter 35, and who is it for?
The Survivors’ and Dependents’ Educational Assistance program (DEA, Chapter 35) provides education and training benefits to the spouse and children of a veteran who is permanently and totally disabled from a service-connected condition, or who died from one. It pays a monthly stipend — over $1,500 a month at the full-time rate — for a set number of months of schooling.
Can my family get both the GI Bill and DEA?
They are separate benefits with separate eligibility, and there are rules about using more than one program for the same person and time period. In many families, one child uses transferred GI Bill benefits while another uses DEA — the right mix depends on your situation, which is exactly what a free review can help you map out.
Does my dependent increase my monthly disability payment?
Yes. Once your combined rating is 30% or higher, the VA adds an amount for a spouse, dependent children, and dependent parents. If your family has grown or you never added your dependents, you may be owed more — and back pay to the date you should have been paid.
Is there health care for my family?
In defined circumstances, yes. Programs like CHAMPVA can provide health coverage to the spouse and children of a veteran who is permanently and totally disabled from a service-connected condition, or who has died from one. Eligibility is specific, so it is worth confirming rather than assuming.
How do I figure out which benefit is worth the most for us?
That is one of the most common questions families ask, and the answer depends on your rating, your service dates, and each family member's plans. An accredited claims agent can review your situation for free and help you compare the options honestly.
What is DIC and who gets it?
Dependency and Indemnity Compensation is a tax-free monthly payment to the surviving spouse and children of a veteran who died from a service-connected condition. The base rate is $1,612.74 per month (2025), with add-ons for children and for a surviving spouse who needs aid and attendance. File with VA Form 21P-534EZ. You do not lose DIC by remarrying after age 57.
Can my family receive both DIC and the Survivors Pension?
No — they are separate programs and you receive one or the other, not both. DIC applies when the death is service-connected; the Survivors Pension applies when it is not but the veteran had wartime service and the family meets income limits. A representative can help you determine which one pays more in your situation.
Still have a question about your own situation?