VA Home Loan — Buy With Zero Down
One of the most valuable benefits you earned: buy a home with no down payment, no mortgage insurance, and competitive rates — for the rest of your life.
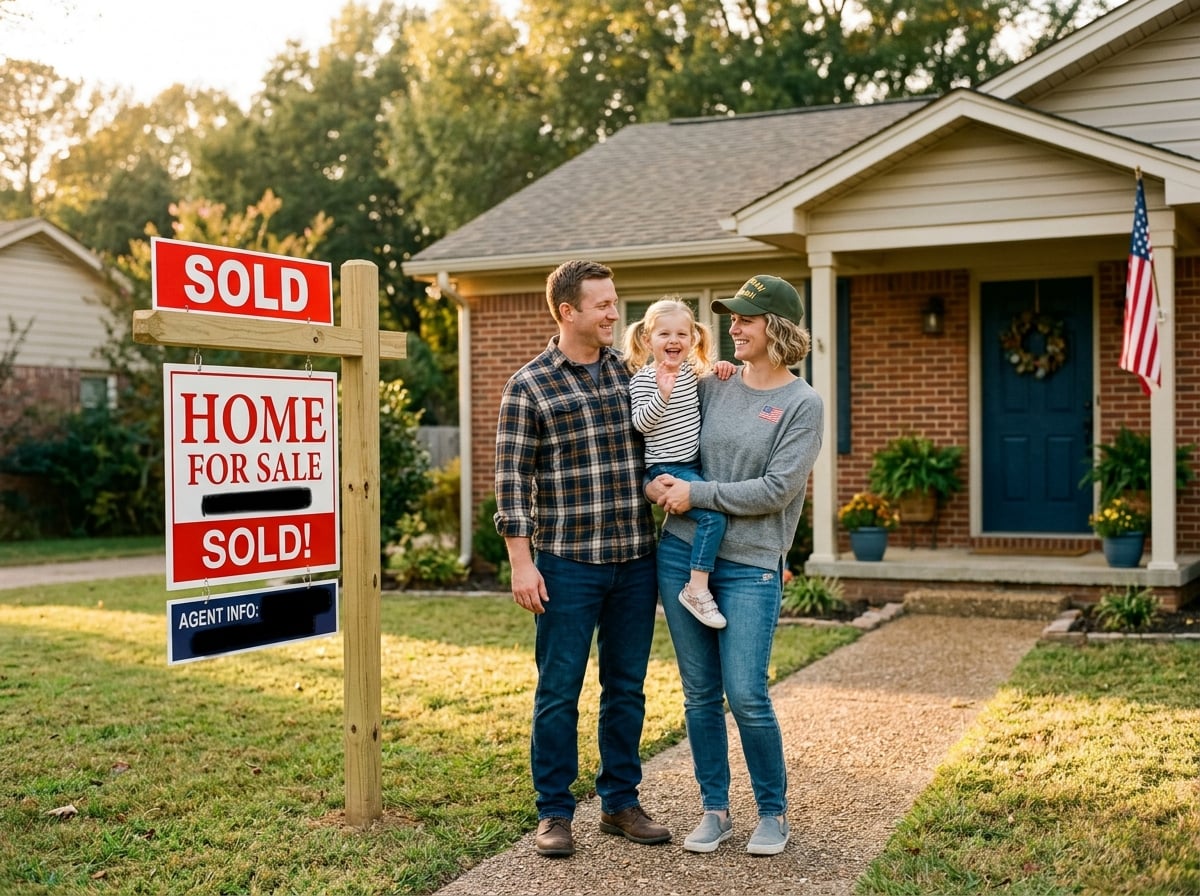
Not every housing story is a crisis. For many women veterans, the question is not “how do I avoid the street” but “how do I finally own something of my own.” The VA home loan is one of the most valuable benefits you earned in uniform, and women veterans use it at lower rates than men — often simply because no one told them how good it is.
A VA-guaranteed loan is not a loan from the VA; it is a loan from a regular lender that the VA backs, which is why lenders can offer terms almost no one else can get: nothing down, no monthly mortgage insurance, and competitive rates.
If you are ready to own a home
One of the most valuable benefits you earned: buy a home with no down payment, no mortgage insurance, and competitive rates — for the rest of your life.
Use the eligibility and application steps on this page to identify the right housing path without leaving the guide.
Understanding VA Home Loan
Zero down payment
For most qualifying purchases, you can buy with no down payment at all. This single feature removes the biggest barrier to homeownership — years of saving for a down payment — and lets you buy now instead of “someday.”
No private mortgage insurance (PMI)
Conventional buyers who put down less than 20% pay PMI every month, often hundreds of dollars. VA loans never require PMI, which can save you a great deal over the life of the loan.
Competitive rates and limited closing costs
VA loans typically carry competitive interest rates, limit the closing costs you can be charged, and have no prepayment penalty. There is a one-time VA funding fee — and it is waived entirely for veterans receiving compensation for a service-connected disability.
A benefit you can use again and again
The VA loan is not a one-time perk. You can use it, pay it off, and use it again; in many cases you can even have more than one at a time. It is a lifelong benefit.
Do you qualify for VA Home Loan?
You meet the VA’s service requirements (length-of-service rules vary by era; many veterans, National Guard, and Reserve members qualify).
You obtain a Certificate of Eligibility (COE) — the document that proves your entitlement to a lender.
You meet the lender’s credit and income requirements (the VA guarantee often makes lenders more flexible than for conventional loans).
The home will be your primary residence — VA loans are for the home you live in, not investment properties.
Surviving spouses of veterans who died in service or from a service-connected disability may also qualify.
Not sure whether you meet these? Eligibility for housing programs turns on details, income limits, discharge status, and how “at risk” is defined. An accredited representative can confirm exactly where you stand before you apply. Reaching out is the one step only you can take.
What VA Home Loan actually gives you
Buying a home
Purchase a house, condo, or VA-approved property as your primary residence with no down payment.
Building or improving
VA loans can be used to build a home or make certain energy-efficient improvements.
Refinancing
Refinance an existing loan to a lower rate (IRRRL) or tap equity with a VA cash-out refinance.
A funding-fee waiver
The one-time VA funding fee is waived for veterans receiving service-connected disability compensation.
What this means for you
Women veterans are among the least likely to use the home-loan benefit they earned — frequently because they simply were not told how powerful it is. If you are stably housed and have ever assumed homeownership was out of reach because you had not saved a down payment, this benefit was built for you. Getting your COE is free and takes minutes.
Getting VA Home Loan, step by step
Get your Certificate of Eligibility (COE)
Apply online at va.gov, through your lender (often instantly), or by mail. The COE proves to the lender that you qualify for the VA guarantee.
Choose a VA-approved lender
Most major lenders offer VA loans. Compare rates and fees — you are allowed to shop around, and you should.
Get pre-approved
The lender reviews your income, credit, and COE and tells you what you can borrow, so you shop with confidence.
Find your home and make an offer
Work with a real-estate agent; a VA appraisal will confirm the home’s value and basic condition.
Close and move in
Finalize the loan, sign, and get your keys — often with nothing down and no monthly mortgage insurance.
What trips women veterans up
Assuming you need a down payment — most VA purchases require none.
Not shopping multiple lenders — rates and fees vary, and you are free to compare.
Forgetting the funding-fee waiver — if you receive service-connected disability compensation, you should not be charged the funding fee.
Believing you can only use it once — the benefit is reusable for life.
VA Home Loan: your questions answered
Do I really need zero down payment?
For most qualifying purchases, yes — the VA home loan allows you to buy with no down payment, which is the single biggest advantage over conventional financing.
Is there mortgage insurance?
No. VA loans never require private mortgage insurance (PMI), even with no down payment. That alone can save hundreds of dollars a month compared to a conventional low-down-payment loan.
What is the funding fee, and can it be waived?
The funding fee is a one-time cost that helps sustain the program. It is waived entirely for veterans who receive compensation for a service-connected disability, and for certain surviving spouses.
Can I use the VA loan more than once?
Yes. The benefit is reusable for life. You can pay off a VA loan and use it again, and in some situations hold more than one at a time.
Official VA & HUD Links
Everything you need is on this page. These official links are provided in addition, so you can go straight to the source to apply or read more.
See every housing program for women veterans, or estimate the rating that could fund your housing stability.